In the world of personal finance, having a good credit score is often likened to possessing a golden key that opens the door to numerous financial opportunities. One of the most compelling options available is the personal loan. For those with a good credit score, personal loans can provide lower interest rates, flexible terms, and the chance to consolidate debt efficiently. However, before diving into this financial endeavor, it’s pivotal to grasp the full scope of what personal loans entail, particularly for individuals with commendable credit histories. In this comprehensive guide, we will explore various facets of personal loans designed for good credit borrowers, offering insights that are both educational and practical.
Understanding The Benefits of Personal Loans for Good Credit
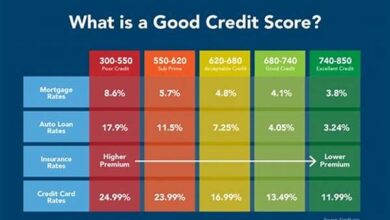
When venturing into the world of personal loans, good credit borrowers stand to gain significantly. One of the primary advantages is access to competitive interest rates. Lenders are more willing to offer lower rates to those with good credit as they are perceived as lower risk. This means that over the life of the loan, borrowers end up paying less in interest compared to those with less favorable credit scores. Another benefit is the potential for more favorable loan terms. Good credit borrowers may enjoy longer repayment periods, which can reduce monthly payment amounts, making it easier to fit into one’s budget. Lastly, personal loans for those with good credit can facilitate debt consolidation. By consolidating existing debts into a single loan with a lower interest rate, borrowers can simplify their repayment process, potentially saving a considerable amount in interest payments alone. Hence, understanding these benefits is crucial for anyone looking into personal loans for good credit: What borrowers should know is that these loans can significantly improve their financial management if handled wisely.
Choosing the Right Lender for Personal Loans
1. Evaluate Interest Rates: When considering personal loans for good credit, borrowers should start by shopping for the best interest rates. Lenders offer competitive rates for those with good credit, but rates can vary significantly.
2. Assess Loan Terms: Good credit borrowers are often offered flexible loan terms. It’s beneficial to understand the length of the loan and any potential penalties for early repayment.
3. Lender Reputation: Look for lenders with a strong reputation for customer service. Personal loans for good credit can be managed more smoothly when a lender provides support and clear communication.
4. Loan Fees: Be aware of any fees associated with the loan, such as origination fees or prepayment penalties. Understanding these can help avoid unexpected costs.
5. Personalized Offers: Seek out lenders who offer terms personalized to your financial situation. This customization is a significant advantage of personal loans for good credit: what borrowers should know is that they have leverage.
The Application Process: What to Expect
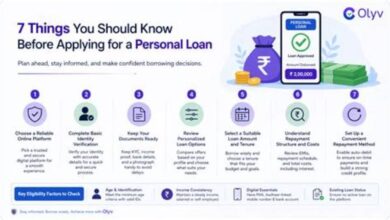
Embarking on the application process for a personal loan necessitates a detailed understanding of what is involved, particularly for individuals with good credit. The first step usually involves gathering personal financial documents, including proof of income, identification, and a detailed list of any outstanding debts. This preparation ensures that the lender can verify the borrower’s creditworthiness swiftly, facilitating a faster approval process. Applicants should also be prepared to undergo a credit check. For those with good credit, this is often a formality but one that reinforces their eligibility for advantageous loan terms. Lenders typically offer pre-approval as an early indicator of eligibility, allowing borrowers to understand potential terms before committing to a full application. Personal loans for good credit: what borrowers should know is that this stage is crucial for setting expectations and ensuring a smooth journey to funding.
Once pre-approved, borrowers will need to focus on choosing the most suitable loan offer based on the terms provided. This involves a detailed evaluation of the interest rates, repayment terms, and any fees associated with the loan. Good credit borrowers are encouraged to negotiate terms where possible, leveraging their strong credit history to obtain the best possible deal. After selecting the optimal loan, the final approval process can follow, wherein the lender may require additional documentation or clarification before disbursing funds. Personal loans for good credit: what borrowers should know includes the importance of diligence in reviewing all loan offer details, ensuring that the final contract aligns with their financial goals and repayment capacities.
Missteps to Avoid When Taking a Personal Loan
Personal loans for good credit can be a formidable financial tool, yet borrowers must avoid common pitfalls to fully benefit from their potential advantages. Firstly, overlooking a detailed comparison among multiple lenders can result in less favorable terms. Good credit should be leveraged to secure not only a low interest rate but also more flexible loan terms. The second misstep lies in disregarding the loan’s total cost, including hidden fees. Unexpected charges can nullify the advantages of a low interest rate. Thirdly, failing to budget for the new debt can strain finances. Even with lower payment amounts, a new loan should fit comfortably within one’s monthly budget. Additionally, borrowers should avoid taking on a loan for non-essential expenses, as this can lead to unnecessary debt accumulation. Lastly, failing to read the fine print can result in unwanted surprises. Fine details about repayment, penalties, and any additional charges should always be reviewed carefully. Hence, personal loans for good credit: what borrowers should know is to remain vigilant and informed to maximize the full potential of the financial product they choose.
Alternatives to Personal Loans for Good Credit Holders
While personal loans are often attractive for those with good credit, alternatives exist that may better serve individual financial needs. A balance transfer credit card could be a cheaper option for those looking to consolidate debt. These cards often come with introductory 0% APR offers, allowing for interest-free debt reduction if paid off in the promotional period. Similarly, a home equity loan or line of credit, like a HELOC, could provide access to funds at lower interest rates, though they come with the risk of home collateral. Peer-to-peer lending platforms also present a viable alternative, where borrowers can potentially secure lower rates through individual lenders rather than traditional banks. Moreover, a personal line of credit provides more flexibility, akin to using a credit card. Understanding these alternatives is crucial within the discussion of personal loans for good credit: what borrowers should know is that the best financial decision is often one that aligns closely with their unique circumstances and financial goals.
The Long-Term Impact of Personal Loans on Credit
Understanding the long-term implications of personal loans is essential for those with good credit seeking to preserve their financial standing. A personal loan, if managed responsibly, can contribute positively to your credit mix, which is a crucial metric in calculating credit scores. Having a mix of credit accounts demonstrates your ability to manage various types of debt and can enhance your credit profile. Timely repayments on a personal loan will bolster your payment history, another significant component of your credit score. Yet, it’s essential to remain diligent. Late payments can have an adverse impact, particularly for individuals starting with good credit scores. Regular, on-time payments are not merely about maintaining a good score but improving it over time. Personal loans for good credit: what borrowers should know is that these loans, while beneficial, also demand a commitment to consistent and responsible financial management for long-term credit health protection.
Ultimately, personal loans for good credit borrowers offer abundant opportunities, yet understanding the broader context and long-term implications is crucial. These loans can enhance financial flexibility, assist in debt consolidation, and improve credit profiles—when approached with care and strategic planning. Borrowers must remain informed and adaptable, reviewing terms and exploring alternatives to ensure their financial decisions today will lead to a prosperous tomorrow.
Conclusion on Personal Loans for Good Credit
To sum up, personal loans for good credit borrowers present a pathway to enhanced financial opportunities. These loans often come with competitive interest rates, facilitating easier debt management and offering the means for varied financial goals such as home improvement, consolidating high-interest debts, or even funding major life events. However, the true benefit lies in understanding the nuances tied to each offer. Personal loans for good credit: what borrowers should know is that they have the advantage yet also the responsibility to choose wisely amidst numerous lenders and terms. By strategically navigating the loan process, comparing offers, and preparing financially, the full benefits of a personal loan can be harnessed effectively. These strategic decisions will help not only in achieving immediate financial objectives but also in maintaining or enhancing one’s credit credibility, ensuring that this beneficial financial standing is not only preserved but fortified for future endeavors.