Navigating the world of personal loans can be a daunting endeavor, especially when faced with the myriad of associated fees. Before hitting submit on that application, it’s vital to comprehend the potential costs involved. Knowing upfront the fees lenders typically impose equips you to make informed choices. In turn, this understanding aids in avoiding unexpected financial surprises. As you venture forth in securing financial support through personal loans, prioritize familiarizing yourself with the Personal Loan Fees You Should Understand Before Applying. This insight guarantees your financial foresight remains unclouded, ensuring an approach that is both strategic and beneficial.
Understanding Origination Fees
One of the primary Personal Loan Fees You Should Understand Before Applying is the origination fee. Charged by lenders for processing a new loan application, this fee often varies between 1% to 8% of the loan amount. It’s typically deducted from the loan disbursal, meaning you receive less than you borrow. Thus, it’s essential to account for this cost in your financial planning. Therefore, inquire about specific origination fees when comparing loans, as they significantly impact the actual cost of borrowing. Understanding this fee enables you to negotiate better terms and manage your expectations effectively.
Common Personal Loan Fees
1. Late Payment Fees: Lenders impose these charges when you miss payment deadlines. Being timely with payments helps you avoid unexpected costs.
2. Prepayment Penalties: Some loans charge a fee if you pay off your loan early. It compensates for the interest the lender loses.
3. Administrative Fees: Administrative tasks related to your loan might incur extra charges, impacting your overall cost.
4. Returned Payment Fees: If a payment bounces due to insufficient funds, expect additional charges, making it crucial to maintain a healthy balance.
5. Annual Fees: Some lenders charge an annual fee for maintaining your loan, adding up over the loan term. Always inquire if this applies.
The Influence of Personal Loan Fees on Your Budget
Balancing the potential impact of Personal Loan Fees You Should Understand Before Applying on your finances is essential. These costs not only affect your monthly payments but also the total interest paid over time. For instance, origination fees might alter your upfront cash flow, requiring adjustments in budgeting. Additionally, the looming threat of late payment fees calls for a meticulous repayment strategy. Streamlining your finances to accommodate these fees ensures you maintain a stable economic footing. When these factors are integrated into your broader financial plan, unforeseen shocks dissipate, enabling sustained fiscal health.
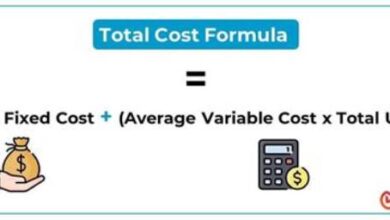
Mismanagement of fees can derail budgets, resulting in financial strain. Therefore, review all costs beforehand. By calculating the total, including interest and fees, you gain a comprehensive view of the loan’s real cost. This strategy prevents oversights and aligns with prudent financial practices. Navigating personal loans with this approach ensures more control and foresight in your financial undertakings, ultimately promoting stability and achievement of set financial goals.
Tips for Reducing Personal Loan Fees
Understanding and reducing Personal Loan Fees You Should Understand Before Applying requires proactive measures. Here are strategies to minimize such costs:
1. Shop Around for Best Rates: Different lenders offer varied fee structures. Comparative shopping is crucial.
2. Negotiate Terms: Lenders might be willing to adjust fees when negotiations are approached knowledgeably.
3. Choose Shorter Loan Terms: While monthly payments might increase, overall fees can significantly reduce.
4. Make Automatic Payments: This reduces the likelihood of late fees and can sometimes result in discounts.
5. Opt for Loans Without Prepayment Penalties: Seek lenders that allow early payment without additional charges.
6. Be Aware of Breadth of Fees: Knowing the complete fee structure enables better decision-making.
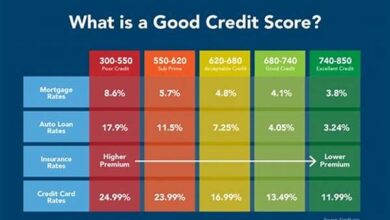
7. Maintain a Strong Credit Score: A higher score gives you leverage in securing lower fees.
8. Review Loan Offers Carefully: Scrutinize terms for hidden fees or clauses before committing.
9. Use Debts Sparingly: Fewer debts reduce the chance of incurring multiple ancillary fees.
10. Consult an Expert: Financial advisors can provide guidance on fee management and reduction.
Evaluating the True Cost of Personal Loans
When considering a personal loan, understanding the nuanced landscape of Personal Loan Fees You Should Understand Before Applying becomes essential. Comprehending how these fees accumulate over the loan’s life is vital. Focusing on the loan’s Annual Percentage Rate (APR) gives insight into the comprehensive cost structure, which includes both interest rates and additional fees. Thus, weighing the total expense rather than simply focusing on monthly payments paves the way for an accurate cost assessment.
Consider how fees alter the affordability of a loan. While a lower interest rate might seem appealing, associated costs could shift the financial balance. Therefore, a loan’s overall cost, factoring in all fees, provides a transparent picture. By evaluating this complete perspective, borrowers can sidestep potential pitfalls and choose options aligned with their financial aspirations. Assiduous evaluation positions you for financially sound decisions, preventing future financial woes and paving a pathway to financial freedom.
Deciphering the Fine Print
When examining the fine print of loan agreements, recognizing Personal Loan Fees You Should Understand Before Applying is crucial. Oftentimes, key details are buried within complex documentation, making it essential to dissect them comprehensively. By dedicating focus to these documents, a clearer picture emerges, allowing you to detect discrepancies and overlooked fees.
Informed borrowers stand a better chance of negotiating favorable terms and avoiding sudden costs. With each clause potentially introducing unexpected fees, scrutiny is your best ally. Seek clarity on all ambiguous terms, and don’t hesitate to ask lenders for explanations. This diligence not only instills confidence but also ensures every fee aligns with your financial constraints and expectations. Mastering this approach transforms you from a passive applicant to an empowered, savvy borrower poised for success.
Conclusion: A Holistic Approach to Loan Applications
In conclusion, the process of securing a personal loan presents a landscape dotted with numerous financial intricacies, notably the Personal Loan Fees You Should Understand Before Applying. Grasping these fees empowers borrowers to navigate this landscape proficiently, ensuring informed decision-making aligns with their fiscal ambitions. By embracing a holistic strategy that integrates thorough comprehension of fees, diligent financial planning, and informed negotiations, borrowers stand poised to tackle the challenges inherent in loan procurement.
This path not only optimizes loan conditions but also nurtures greater financial autonomy and security. Through the conscientious evaluation of personal loan fees and a commitment to strategic management, financial goals can be achieved with reduced stress and enhanced peace of mind. In mastering an understanding of loan fees, you lay the groundwork for sustained economic well-being, crafting a future where financial decisions bolster rather than hinder your aspirations.