In today’s financial landscape, understanding the total cost of a personal loan is crucial for making informed borrowing decisions. Personal loans can be a convenient solution for financing various needs, from medical expenses to home renovations. However, comprehending the actual cost of borrowing is vital to avoid unforeseen financial burdens. By learning How to Calculate the Total Cost of a Personal Loan, you can ensure that you are making a financially sound decision. This article will guide you through the process, providing detailed insights and tips to help you navigate the complexities of personal loan costs.
Factors Influencing the Total Cost of a Personal Loan
When considering How to Calculate the Total Cost of a Personal Loan, it is imperative to recognize the numerous factors that contribute to the overall financial commitment. Firstly, the interest rate plays a pivotal role in determining the long-term cost, with higher rates resulting in increased payments over time. Additionally, the loan term, or the period over which the loan is to be repaid, will significantly impact the total cost, as longer terms generally lead to more interest accumulation. Fees and charges associated with loan processing, such as origination and application fees, further contribute to the total expenditure. By evaluating these components in detail, you can obtain a comprehensive understanding of the actual financial obligation, ensuring you are adequately prepared for the repayment journey.
Understanding these factors requires meticulous analysis and a critical approach to each element. An insightful strategy involves comparing multiple loan offers, paying attention to the annual percentage rate (APR) which reflects the true yearly cost of borrowing, inclusive of fees. Armed with this knowledge, you can effectively gauge which loan aligns with your financial capability and long-term goals. As you consider How to Calculate the Total Cost of a Personal Loan, strive to maintain a clear perspective on your overall budget, aiming for a sustainable and manageable repayment plan.
By thoroughly investigating the influence of these factors, borrowers can mitigate potential financial pitfalls and enhance their foresight regarding future investment opportunities. In summation, fully grasping How to Calculate the Total Cost of a Personal Loan involves a holistic evaluation of all borrowing aspects combined. Taking a proactive stance and being informed about the intricacies of loan costs will empower you to make prudent financial choices.
Steps to Accurately Calculate Your Personal Loan Costs
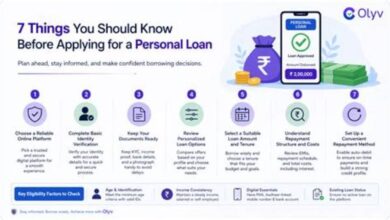
1. Identify the Interest Rate: The first step in learning How to Calculate the Total Cost of a Personal Loan is determining the applicable interest rate, which directly affects your total repayment amount over the loan term.
2. Understand Loan Term Length: Consider how the duration of your loan influences the total cost—shorter terms generally mean higher monthly payments but less overall interest.
3. Include All Fees: Don’t overlook the importance of factoring in additional fees such as origination, processing, or late payment fees that could increase the total loan cost.
4. Calculate APR: The APR provides a comprehensive view of your loan cost by including both the interest rate and any additional fees, giving a true picture of your borrowing expense.
5. Use a Loan Calculator: Employing an online loan calculator is a practical way to visualize how different rates, terms, and fees impact the overall cost, assisting in precise calculations.
Importance of Accurate Loan Cost Calculation
Accurate calculation of the total cost of a personal loan ensures transparency, allowing you to anticipate and prepare for future financial commitments. The thorough understanding gained by learning How to Calculate the Total Cost of a Personal Loan empowers you to select offerings that align closely with your financial objectives and lifestyle. Notably, this knowledge helps in preventing potential debts that may arise from underestimated payments or overlooked fees. Moreover, precise calculations enable strategic debt management, avoiding the pitfalls of overborrowing and ensuring a secure financial future.
Being well-versed in loan cost calculations also enhances your negotiating power with lenders. When you present a clear picture of what you are willing to pay and the terms you can manage, you pave the way for potentially more favorable interest rates or terms. As such, the skill of accurately determining your loan’s total cost is both a protective and proactive measure in the realm of personal finance. It plays a pivotal role in maintaining financial health and reinforcing the quality of your credit profile.
Common Pitfalls in Estimating Personal Loan Costs
1. Ignoring Additional Fees: Fees such as prepayment penalties or late fees can drastically alter the total cost of a personal loan if not accounted for.
2. Underestimating Loan Term Impact: Longer loan terms may offer lower monthly payments but can significantly increase the total interest paid over time.
3. Misinterpreting APR: Not understanding the true purpose of the APR can lead to an inaccurate calculation of the total loan cost.
4. Neglecting Variable Rates: Loans with variable interest rates can fluctuate, potentially increasing your costs unexpectedly if rates rise.
5. Overlooking Optional Insurance: Insurance or payment protection plans can add to your monthly payment and the overall cost, which some borrowers might overlook when focusing solely on interest rates.
6. Forgetting to Compare Offers: Failing to shop around for the best rates and terms can result in selecting a loan that is not the most cost-effective option.
7. Misjudging Payment Capability: Overestimating your ability to meet repayments can lead to increased costs from late payments or loan restructuring.
8. Disregarding Early Payment Fees: Some loans penalize early repayments, which could negate the benefits anticipated from paying off a loan sooner.
9. Relying Solely on Monthly Payments: Focusing only on the affordability of monthly payments without considering the total loan cost can be misleading.
10. Neglecting Currency Exchange Rates: For international loans, exchange rates can fluctuate, affecting how much you ultimately pay.
Comprehensive Tips on Loan Cost Evaluation
Understanding how to calculate the total cost of a personal loan is an essential skill that holds significant implications for your financial health. When you delve into how to calculate the total cost of a personal loan, consider engaging with reliable financial tools designed specifically for loan analysis. These tools, such as detailed loan calculators, can provide insight into the potential variations in cost due to fluctuations in interest rates or changes in loan terms. Engaging with these resources not only streamlines the calculation process but provides a layer of accuracy and confidence in your financial planning.
Additionally, maintaining transparent communication with lenders can reveal insights into hidden costs or fees not immediately apparent in loan agreements. Always prioritize lenders who are open and forthcoming with detailed breakdowns of loan costs. As you explore how to calculate the total cost of a personal loan, don’t hesitate to reach out for professional financial advice, ensuring that your calculations align with your overall financial strategy and long-term goals. This detailed approach to evaluating personal loan costs not only fosters financial prudence but ultimately enriches your financial literacy and capacity to manage debts effectively.
Emphasizing these strategies in your loan cost evaluation process can help safeguard your financial well-being against the unexpected twists and turns of borrowing. Being thoroughly prepared and educated on the intricacies of loan costs ensures you have complete control over your financial path, minimizing risk and optimizing outcomes.
In-Depth Guide to Personal Loan Cost Components
An essential aspect of understanding How to Calculate the Total Cost of a Personal Loan lies in a detailed examination of the individual components contributing to the overall financial obligation. By evaluating each of these aspects, borrowers can obtain a clear, nuanced perspective of their financial commitment. Critically, the interest rate forms the foundation, dictating the portion of payments that go towards interest and affecting the overall expense significantly. Fees, whether they be origination fees, late payment penalties, or processing charges, also warrant careful scrutiny, as they can substantially increase the cost beyond the principal amount.
The term length and payment schedule further influence how interest accrues, offering a delicate balance between affordable monthly payments and minimized interest costs. Borrowers must also consider the implications of variable rates or prepayment penalties, which could significantly alter the financial landscape if not properly accounted for. Engaging with each of these components ensures a thorough understanding of How to Calculate the Total Cost of a Personal Loan, facilitating informed decision-making and robust financial planning.
A comprehensive grasp of these elements is instrumental for negotiating favorable loan terms or adjustments with financial institutions. Borrowers who engage deeply with cost component analyses gain an upper hand, equipped with knowledge that can lead to cost savings and improved loan experiences. Consequently, education on How to Calculate the Total Cost of a Personal Loan is not only beneficial but essential for sound financial health.
Conclusion: Mastering Loan Cost Calculations
In conclusion, mastering How to Calculate the Total Cost of a Personal Loan is a crucial skill for any borrower. By approaching the task with diligence and a commitment to understanding all contributory factors, individuals can ensure they make informed choices that align with their financial circumstances and goals. Whether through evaluating interest rates, terms, or additional fees, a thorough understanding of the total cost paves the way for successful financial management and planning.
Ultimately, the ability to accurately determine the total cost of a personal loan empowers borrowers to navigate the complexities of personal finance with confidence. By prioritizing a complete and detailed evaluation of all associated costs, one can avoid the pitfalls of unexpected financial obligations, fostering a stable and prosperous financial future. This proficiency stands as an invaluable asset, transforming loan agreements from daunting challenges into manageable elements of a broader financial strategy.