Securing a personal loan can be a critical step for improving your financial health or achieving personal dreams. However, gaining approval is not always guaranteed. Lenders assess numerous factors before approving a loan application, and understanding these components can significantly improve your chances of success. Whether you need a personal loan for consolidating debts, covering a large purchase, or managing unexpected expenses, following several key strategies can enhance your probability of getting approved.
Understand Lender Requirements
How to Improve Your Chances of Getting a Personal Loan begins by understanding the specific requirements set by lenders. Each financial institution has criteria concerning credit scores, income levels, and debt-to-income ratios. A solid grasp of these factors can help tailor your application to meet lender expectations. Much like a resume, clarity and alignment to the lender’s checklist demonstrate preparedness and financial responsibility. Moreover, consistently monitoring your credit report ensures accuracy and reflects your commitment to responsible borrowing.
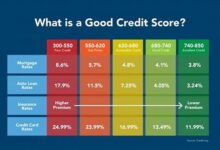
While income indicates your ability to repay, your credit history provides insights into your financial behavior. A high credit score positions you favorably as a low-risk borrower. Therefore, it is wise to request your credit report in advance, rectify discrepancies, and ensure all your accounts reflect positively. This proactive approach minimizes obstacles and fosters confidence in lenders, thereby increasing your chances for loan approval.
Maintain a Healthy Credit Score
1. Pay Bills on Time: Timely bill payments are vital for maintaining a healthy credit score. Late payments can significantly impact your score, hence how you handle your existing debts can improve your chances of getting a personal loan.
2. Reduce Debt: Lowering your existing debts can significantly boost your credit score. When lenders see a lower debt-to-income ratio, it translates into your ability to manage finances responsibly, thereby enhancing approval prospects.
3. Limit Credit Inquiries: Frequent credit inquiries can negatively impact your credit score. Space out your credit applications judiciously to maintain a healthy score, thereby improving your chances of getting a personal loan.
4. Use Credit Wisely: Keep your credit utilization ratio low by not maxing out your credit. This disciplined approach enhances your credit standing, which is crucial for loan applications.
5. Regularly Review Credit Reports: Consistently monitor your credit report for inaccuracies. Correcting errors proactively can lead not only to a better credit score but also to a higher likelihood of loan approval.
Prepare Proper Documentation
Proper documentation is crucial when it comes to How to Improve Your Chances of Getting a Personal Loan. Lenders require specific documents to verify income, employment status, and identity, among other things. Gathering these documents in advance demonstrates preparedness and speeds up the application process. Typical documents might include pay stubs, tax returns, employment verification, and banking statements. Providing clear and organized paperwork reflects your attention to detail and commitment to transparency, which are attractive traits to lenders.
Anticipating what a lender might require also reduces the back-and-forth during the application process. When possible, obtain pre-approval from the lender. This step acts as a preliminary check, providing you with insights into your borrowing standing. Understanding such criteria aligns your application closely with lender expectations and smooths the pathway towards successful approval. Being well-prepared not only expedites processing but also reflects well on your application profile.
Choose the Right Lender
Choosing the right lender is a critical step in how to improve your chances of getting a personal loan. Researching lending institutions that specialize in personal loans, understanding their terms, interest rates, and customer reviews can guide you to a favorable choice. Different lenders provide varied benefits and conditions, matching your needs to the right lender increases the probability of successful approval.
1. Research Various Lenders: Each financial institution has its own terms and loan products. Researching minimum credit score requirements and interest rates allows for informed decision-making and enhances the chances of approval.
2. Consider Credit Unions: Credit unions often have lower interest rates and manageable terms compared to traditional banks. When aligning yourself with a credit union, you can secure better loan conditions.
3. Explore Online Lenders: Many online lenders provide competitive rates and flexible terms. Such platforms might offer quick approval processes, tailored loans, and less rigorous credit requirements.
4. Visit Banks with Existing Relationships: Establishing prior relationships with traditional banks might make them more willing to approve a loan, as they already have insights into your financial behavior and history.
5. Consider Peer-to-Peer Lending: These platforms connect borrowers directly with individual investors, offering potentially lower interest rates and flexible repayment terms.
6. Check Loan Terms & Conditions: Understanding the terms of the loan, including repayment periods and fees, ensures realistic commitments, improving chances of approval in the eyes of lenders.
7. Know Your Financial Standing: A thorough analysis of your financial health can guide you in choosing a lender whose terms align best with your current situation.
8. Peer Recommendations: Hearing experiences from friends or family who have secured loans successfully can provide valuable insights into selecting a fitting lender.
9. Consult Financial Advisors: Seeking advice from financial experts can help you navigate the maze of loans, ultimately improving your chances of getting a personal loan.
10. Align Loan Purpose with Lender Specialties: Some lenders tailor their products to specific loan purposes. Matching your needs with lender specialties ensures you receive not only approval but also favorable terms.
Demonstrating Financial Stability
When considering how to improve your chances of getting a personal loan, demonstrating financial stability plays a significant part. Lenders look favorably upon applicants who can show a steady income, effectively manage existing debts, and exhibit savings behavior. Regular income and a stable job demonstrate your ability to meet loan repayments, serving as strong indicators of a reliable borrower. Maintaining employment over a long period provides reassurance to lenders that your income stream is both predictable and sustainable.
Building a robust financial narrative that includes savings and asset accumulation further underscores creditworthiness. Savings reflect discipline and preparedness for any financial contingencies. This financial safety net reassures lenders of your competence in managing finances. Moreover, having a financial plan in place—detailing income, expenses, liabilities, and potential growth areas—is not only practical but also offers lenders a transparent view of your financial health.
Essential Tips for Securing a Personal Loan
How to improve your chances of getting a personal loan hinges on several key strategies that optimize your financial profile to meet lender criteria. Being proactive in managing your credit score, maintaining financial stability, understanding lender requirements, and choosing the right lender all form part of a comprehensive approach to securing loan approval. These steps help create a strong borrower profile that not only enhances chances of approval but also impacts the quality and terms of the loan offer.
Building long-term financial habits such as consistent saving, responsible credit use, and continual financial education will enhance your overall financial landscape. These strategies aren’t just about increasing your chances of a loan approval today, but also ensure financial wellness throughout one’s life. By addressing these crucial financial aspects, one positions themselves as an appealing candidate for any personal loan opportunity.
Conclusion
Securing a personal loan can be simplified with a clear understanding of how to improve your chances of getting a personal loan. By meticulously preparing financial documents, improving credit standing, and selecting the right lender, borrowers can facilitate the loan application process successfully. Aligning one’s financial profile with the expectations of lenders enhances both the likelihood of approval and the quality of loan terms offered.
Establishing strong financial practices isn’t solely for loan approval purposes but for sustained financial health. Responsible financial management, regular monitoring, and continuous learning form the bedrock for prospering in today’s financial landscape. Taking these steps not only improves loan prospects but also ensures a robust financial standing capable of weathering future challenges.